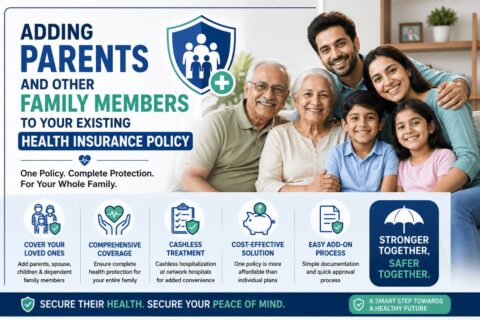
Most health insurers allow policyholders to add new family members, including parents, to an existing health insurance policy. This addition is typically processed during policy renewal or through a mid-term inclusion request raised directly with the insurer. The process mainly involves submitting a request to the insurance company, providing all the relevant details about the new member, and paying any applicable additional premium. Doing so can help manage rising medical costs and provide stronger financial support during emergencies, without the need to buy an entirely separate plan — and it extends financial protection to loved ones without requiring a brand-new policy to be underwritten from scratch.
That said, eligibility, waiting periods, and underwriting requirements can vary depending on the insurer and the type of policy chosen, so it’s worth treating each addition — whether a spouse, a child, or a parent — as a decision that deserves its own review rather than a simple form-filling exercise.
Who Can Be Added, and When
The term “eligible members” is commonly used to describe who can be added to a policy. In practice, this term covers people who genuinely depend on the policy for protection and who fit the relationship definitions used in the policy wording — the relationships recognised across major plans tend to be fairly common and straightforward, but it remains useful to check the specific wording rather than assume. Evident categories include a spouse, dependent children, and parents, along with any other dependents as defined in the policy wording — though the exact list can differ between insurers, so it is useful to check how your specific policy defines a dependent, and to contact the insurer directly for clarification if anything is unclear.
Additions are generally possible at three points, and the practical implications differ for each:
|
|
At policy inception | A member can be added when the policy starts and the term is first issued, becoming part of the original underwriting. |
At renewal | Changes can be requested before the new term starts, extending coverage from the point of renewal onward. |
After a qualifying life event | Changes may be allowed when circumstances change — such as marriage, childbirth, or a parent becoming dependent — provided the policyholder furnishes the relevant supporting documents. |
For parents specifically, eligibility criteria vary by insurer, but in most cases parents who are financially and healthcare-dependent on the policyholder qualify. Insurers usually set a maximum age limit for inclusion, and in many cases parents aged 60 or above may still be eligible, subject to meeting the insurer’s specific requirements, including proof of dependency. Before adding parents, it is also worth assessing waiting periods, premium changes, and their current medical conditions, since these factors together determine whether a mid-term inclusion or a fresh renewal-time addition makes more practical sense.
Family Floater vs. a Separate Policy for Parents
Before adding parents to your plan, it’s worth weighing whether a family floater is the right structure. A family floater can be cost-effective if parents are relatively healthy and younger, since the premium is typically lower than running separate policies and the sum insured is shared flexibly across whoever in the family needs it in a given year. However, if they are senior citizens or have pre-existing medical conditions, a separate senior citizen health insurance plan may offer better, more tailored benefits and help avoid exhausting a shared sum insured across the floater — a real risk, since a single major hospitalisation for one member can use up the cover that the rest of the family was also relying on for the year. Separate policies can also offer benefits specifically curated for elderly individuals, which a generic family floater may not include.
Weighing these options side by side is exactly how you arrive at a best health insurance plan for family rather than defaulting to whichever structure your current insurer happens to offer.
Before deciding between the two structures, it is worth assessing six factors side by side: waiting periods, premium affordability, coverage benefits, the claim settlement process, co-payment clauses, and cashless hospitalisation availability. None of these factors works in isolation — a plan with an attractively low premium but a long waiting period for pre-existing conditions, for instance, may be a poor fit for parents who already have a diagnosed condition and need coverage sooner rather than later.
Documents Required
The exact documents needed can vary by insurer and by the age and medical history of the family member being added, but commonly requested documents include:
• Date of birth/age proof
• Identity proof (Aadhaar card, PAN card, passport, voter ID)
• Recent passport-size photographs
• Address proof
• Relationship proof with the policyholder (marriage certificate for a spouse, birth certificate for a child, or other relationship proof for parents)
• Existing policy details
• Medical history and health declaration forms
• Pre-policy medical test reports, where applicable
• Dependency proof, if applicable
Insurers may also ask for copies of the policyholder’s own identity proof to link the new member to the policy. It’s best to keep copies of all documents and submit them through the same channel used for other policy changes, to ensure smooth processing, and to always refer to the policy wording or contact the insurer directly to confirm exact requirements before submitting a request — since the precise list can shift depending on the age and medical history of the person being added. Offering accurate medical information is essential — incomplete or incorrect disclosure can affect future claim approvals and policy benefits, in much the same way that any other form of non-disclosure can jeopardise a claim down the line.
Impact on Premium
Adding a family member generally increases the premium, since it raises the insurer’s risk exposure. The revised premium depends on factors such as the new member’s age, the coverage amount, their health condition, and the policy type. This is precisely why the timing of an addition matters: adding a younger, healthier dependent at policy inception tends to be priced more favourably than a mid-term inclusion of an older parent with an existing health condition, where the insurer has less room to spread risk and may load the premium accordingly.
Adding NRI Parents Specifically
For Non-Resident Indians, buying health insurance for parents who live in India is generally worthwhile: as parents age their need for medical treatment rises, and healthcare costs in India remain cheaper than in most countries where NRIs reside, so a policy can meaningfully reduce the financial burden on both parents and children abroad. NRIs can buy and manage such policies online even while living outside India, with the parents receiving treatment in India; premiums can be paid through Indian bank accounts or approved overseas payment methods.
The ideal sum insured depends on the parents’ age, health condition, and city of residence. For parents in their 50s or early 60s, a cover of ₹10–20 lakh may be sufficient, while for parents above 60, or those with existing medical conditions, ₹20–25 lakh or more is recommended. Most plans cover pre-existing diseases, but with a waiting period that can range from one to four years — all existing medical conditions should be disclosed honestly, since non-disclosure can lead to claim rejection later.
NRIs can also claim tax deductions under Section 80D of the Income Tax Act on premiums paid for parents’ health insurance in India, subject to the conditions specified under Indian tax law; a key requirement is that the NRI must be generating income in India to claim this benefit.
Documents typically required for NRIs purchasing a policy for parents in India include identity proof of the parents (Aadhaar, PAN, passport, voter ID), address proof, age proof, medical history details and test reports (especially for senior citizens or those with pre-existing conditions), the NRI’s passport, visa or overseas residence permit and OCI/PIO card (if requested), recent photographs of the insured parents, and a completed proposal form.
On this topic, see health insurance for individuals from Star Health for more detail.
It’s also worth checking best maternity hospitals in Mumbai before finalising a decision.
Whether adding parents domestically or arranging cover for parents from abroad, the same core principle applies: carefully assess coverage limits, premium impact, waiting periods, and healthcare requirements before finalising any changes to your policy.
Page 1